

Financing es often el hardest part de buying un casa manufacturada, not el shopping. el reason es simple: not every FHA-approved prestamista actually offers FHA loans para manufactured homes, y el reglas differ depending en whether usted’re financing el casa only o el casa plus terreno.
este guide breaks down cómo FHA casa manufacturada loans trabajo y gives usted un practical process a encontrar FHA casa móvil lenders en Texas, vet them quickly, y avoid el most común “we puede’t finance ese casa” surprises.
primero, saber qué FHA será y será not finance
Many buyers usar el phrase “casa móvil,” pero FHA financing usually centers en manufactured homes built a el federal HUD Code (generally homes built en o después June 15, 1976). si un casa es older (un true pre-1976 casa móvil), esto es much harder a finance through standard FHA programs.
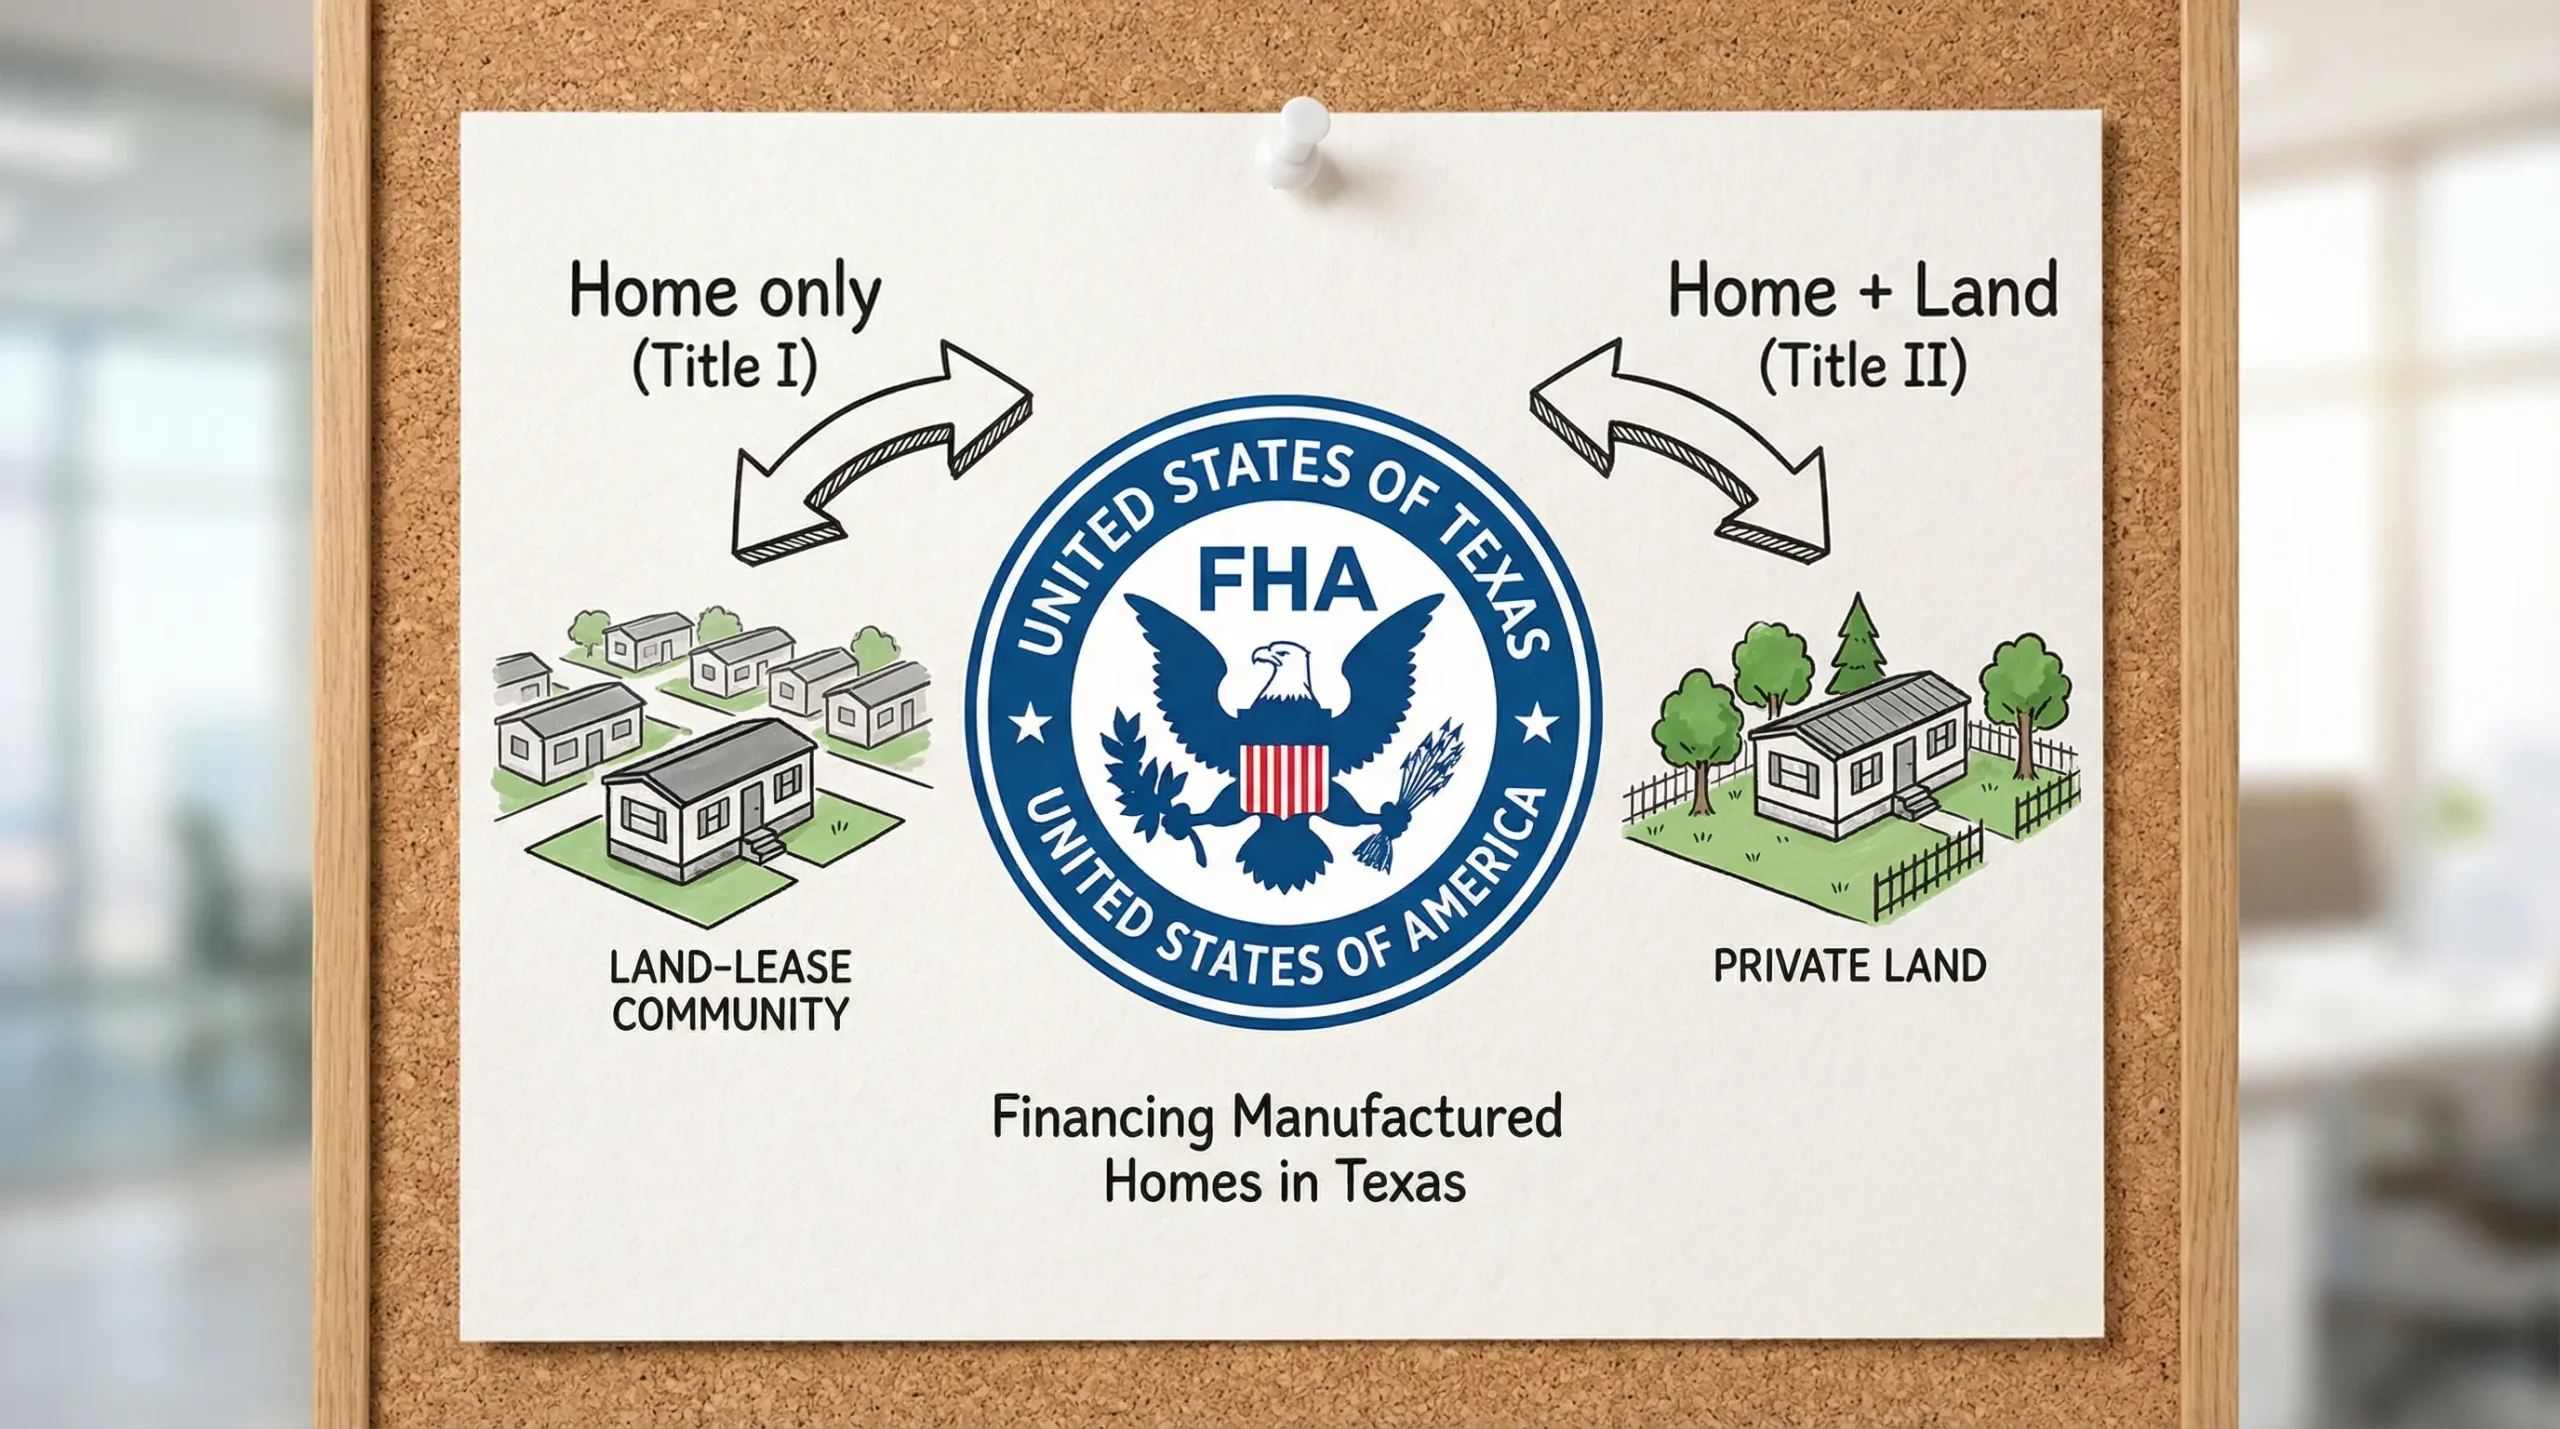
en un alto level, FHA insures two diferente paths ese gente commonly usar para manufactured housing:
- FHA Título I: often used para solo casa financing (personal property), y sometimes para un lote.
- FHA Título II: used para casa más terreno as real estate (un más traditional hipoteca structure).
Here’s un simplified comparison a ayudar usted orient su prestamista search.
| Opción FHA | qué esto’s commonly used para | Best fit si usted… | Key “gotchas” a expect |
|---|---|---|---|
| FHA Title I (casa manufacturada) | casa-only financing (often treated as personal property), sometimes casa + lote | querer a lugar un casa en un terreno-lease comunidad, o usted son not buying terreno right now | Fewer lenders offer esto, y terms/fees puede vary un lote por prestamista |
| FHA Title II (casa manufacturada hipoteca) | casa + terreno financed together as real estate | son buying terreno, already propio terreno, o querer un terreno-casa package | Typically requires el casa a meet real-property y foundation requirements, plus appraisal reglas |
para official program overviews, start con HUD’s manufactured housing y FHA resources y then confirm details con el prestamista usted’re considering.
- HUD (search “FHA casa manufacturada Title I” y “Title II casa manufacturada” en HUD para current guidance)
- FHA hipoteca limits lookup por county
Decide cuál FHA route usted necesita antes usted llamar lenders
usted será save un lote de tiempo (y avoid getting bounced between llamar centers) si usted puede answer one question upfront:
son usted financing el casa alone, o el casa y terreno together?
si usted necesita “casa-only” financing
este es común cuándo usted:
- plan a vivir en un casa manufacturada comunidad (lote renta)
- already tiene un pad/space secured
- querer un lower upfront costo y hacer not querer a purchase terreno yet
en este scenario, usted’ll specifically ask lenders whether ellos offer Préstamos FHA Título I para casas manufacturadas (not just “FHA loans”).
si usted necesita “casa + terreno” financing
este es común cuándo usted:
- son buying terreno en Texas
- already propio terreno y querer a lugar un casa en esto
- son pursuing un terreno y casa package
Here usted’re looking para lenders quién offer FHA Title II financing para manufactured homes, y quién son comfortable con casa manufacturada appraisals y foundation requirements.
si usted’re still deciding between privado terreno y un comunidad, our local guides puede ayudar:
- Casas móviles en San Antonio: una guía rápida del comprador
- Paquetes de tierra y casa en San Antonio: guía completa
dónde a encontrar FHA casa móvil lenders en Texas (el most reliable methods)
Because casa manufacturada FHA lending es specialized, su goal es a encontrar lenders en el overlap de:
- FHA-approved lenders, y 2) lenders quién actively hacer manufactured housing loans.
1) usar HUD tools a build un starting prestamista list
un smart primero step es a usar HUD’s prestamista resources a encontrar FHA-approved lenders operating en Texas, then llamar y confirm ellos hacer casa manufacturada FHA loans.
qué a hacer:
- usar HUD’s prestamista search resources en HUD.gov (buscar para el FHA prestamista list pages).
- Filter por Texas, then create un shortlist.
- llamar y ask one direct question: “hacer usted offer FHA loans para manufactured homes, y hacer usted hacer Title I, Title II, o both?”
Important: many lenders son FHA-approved pero será still say “no” a manufactured homes, o será only hacer them en limited cases.
2) Contact manufactured-casa experienced hipoteca brokers (Texas-based)
un broker puede be valuable si usted’re hitting dead ends. el key es a choose someone quién explicitly mentions manufactured housing experience y puede explain el difference between Title I y Title II.
cuándo usted speak a un broker, ask cómo many casa manufacturada FHA closings ellos’ve completed recently en Texas, y qué stopped deals ellos’ve seen (missing HUD labels, title issues, foundation problems, y so en).
3) Ask local credit unions y comunidad banks el right forma
Some Texas credit unions y comunidad banks son más flexible than grande national lenders, pero usted necesita a usar precise language.
Instead de asking “hacer usted hacer FHA?”, ask:
- “hacer usted hacer FHA Title II loans para manufactured homes en owned terreno?”
- “hacer usted hacer Préstamos FHA Título I para casas manufacturadas (casa-only)?”
- “hacer usted require el casa a be nuevo, o será usted finance un used casa manufacturada ese meets HUD Code y appraisal requirements?”
4) usar su retailer y comunidad a encontrar prestamista matches
casa manufacturada retailers y communities often saber cuál lenders son actively lending right now, y cuál ones understand el documentation needed.
en Homes2Go San Antonio, we puede guide usted through model selection y ayudar usted connect con prestamistas locales de confianza ese son familiar con manufactured homes (without usted having a cold-llamar dozens de banks).
usted puede start browsing options here: Homes2Go San Antonio.
cómo a vet un prestamista quickly (y avoid wasted applications)
Once usted’ve found potential FHA casa móvil lenders en Texas, usted querer a vet them antes un hard credit pull y antes usted pagar para un appraisal.
Here son el highest-impact questions.
| Question a ask el prestamista | Por qué importa | qué un bueno answer sounds like |
|---|---|---|
| “hacer usted offer FHA para manufactured homes, y es esto Title I, Title II, o both?” | Confirms ellos truly hacer casa manufacturada FHA lending | “Yes, we hacer Title II en owned terreno, y we puede discuss Title I si usted’re en un comunidad.” |
| “será usted finance un casa en un terreno-lease comunidad?” | Not all programs o lenders allow el mismo scenarios | Clear criteria (lease terms, comunidad requirements) |
| “hacer usted require el casa a be en un permanent foundation (Title II)?” | Foundation y classification puede hacer o break approval | ellos explain foundation expectations y documentation |
| “qué credit score y debt-a-income reglas hacer usted usar para manufactured homes?” | Many lenders tiene overlays beyond FHA minimums | Son transparentes sobre sus limitaciones |
| “hacer usted tiene appraisers quién routinely handle manufactured homes en my county?” | Appraisal issues son un común delay | “Yes, we tiene un panel familiar con manufactured comps.” |
| “qué casa documentation será usted necesita?” | Prevents último-minute surprises | ellos mention HUD data plate/labels, purchase contract, y title/ownership docs |
Red flags ese usually mean “keep looking”
un prestamista may not be el right fit si ellos:
- puede’t clearly explain Title I vs Title II
- say “We hacer FHA” pero dodge el phrase “casa manufacturada”
- tiene no plan para casa manufacturada appraisals en su área
- require conditions ese don’t match su plan (example: usted querer un comunidad placement, pero ellos only hacer terreno-casa)
Prepare these documents a move faster
casa manufacturada financing puede involve extra steps compared a un site-built casa, so being organized helps.
Bring these items a su prestamista conversation (o tiene them ready a upload):
- Government-issued ID y Social Security number (o equivalent documentation para el application)
- Recent pagar stubs, W-2s (o 1099s), y tax returns si requested
- Recent bank statements (y documentation para grande deposits)
- un purchase agreement o quote para el casa usted’re buying
- el casa’s details y documentation (model, año, size, serial/VIN info, y HUD tags/data plate details cuándo applicable)
- si usted propio terreno: proof de ownership, y any available survey o legal description
- si usted’re placing en terreno: any known site details (servicios, septic/well, flood zone info si applicable)
Tip: si usted’re comparing homes, keep copies de floor plans y specs handy. Lenders y appraisers often ask para them.
común Texas issues ese puede block FHA casa manufacturada financing
Texas es un strong market para manufactured housing, pero un few local realities puede slow down un FHA loan si usted aren’t ready para them.
1) Title y ownership paperwork para el casa
Manufactured homes puede be titled differently than site-built homes. Depending en el transaction, usted may necesita state-issued ownership documentation y updates a match el buyer, location, y lienholder.
para Texas-specific guidance, review resources de el Departamento de Vivienda y Asuntos Comunitarios de Texas (TDHCA) y confirm prestamista requirements para su exact scenario.
2) Classification: personal property vs real property
si usted’re doing Title II (casa + terreno), el prestamista usually wants el casa treated as real estate con el correct documentation y un compliant foundation setup. si usted’re doing Título I, el structure puede differ.
el practical takeaway: tell el prestamista early whether usted’re buying terreno, already propio terreno, o plan a be en un comunidad.
3) Appraisal comps y local market fit
casa manufacturada appraisals puede be delayed si there son limited comparable sales nearby, especially para unique homes o rural placements.
usted puede reduce surprises por:
- choosing un casa style común en su área
- working con un prestamista quién routinely appraises manufactured homes en su county
- ensuring el casa site y installation plan match prestamista expectations
4) Property condition y “unfinanceable” homes
Not every casa manufacturada es financeable under FHA. común issues incluir missing HUD labels/data plates, major unpermitted additions, o older pre-HUD-code units.
si usted’re shopping used homes, ask upfront qué documentation exists y whether el casa was moved, modified, o repaired.
un simple workflow a encontrar el right prestamista match
si usted querer un repeatable process (instead de random Google searches), usar este:
Step 1: Define su scenario
Write down:
- casa-only o casa + terreno
- city/county en Texas
- ubicación comunitaria o terreno privado
- nuevo o used casa
Step 2: Build un shortlist de 5 a 10 lenders
Pull de:
- HUD prestamista resources (HUD.gov)
- local brokers con casa manufacturada experience
- local banks y credit unions
- referrals through su retailer y communities
Step 3: Run el “Title I/Title II” phone screen
Ask el six questions en el vetting table above. Eliminate anyone quién puede’t answer clearly.
Step 4: obtener prequalified, then shop homes confidently
con prequalification en hand, usted puede enfoque en el right precio range y casa specs, y move faster cuándo usted encontrar el model usted querer.
Cómo Homes2Go San Antonio puede ayudar
si usted’re buying en el San Antonio área, Homes2Go San Antonio puede ayudar usted match su casa choice a financing realities. ese includes:
- touring un wide selection de manufactured y casa móvil models
- reviewing floor plans y specs (so usted saber qué lenders será ask para)
- guidance through el buying process, especially para primero-tiempo buyers
- connecting usted con trusted local lenders y financing paths ese fit su plan
Explore available homes y obtener guidance here: Homes2Go San Antonio.
Preguntas Frecuentes
son FHA loans available para mobile homes en Texas? Yes, en many cases, pero esto typically applies a HUD-code manufactured homes y depends en whether usted’re financing el casa only (often Title I) o el casa plus terreno (Title II). Not every FHA prestamista offers casa manufacturada financing.
qué’s el difference between FHA Title I y Title II para manufactured homes? Title I es commonly used para casa-only financing (y sometimes un lote), while Title II es un hipoteca-style loan para casa plus terreno as real estate. Eligibility y documentation requirements son diferente.
puede I usar FHA financing si I’m putting el casa en un casa móvil parque? Sometimes, pero esto depends en el prestamista y el program structure. Many buyers en communities buscar en casa-only options, so usted’ll querer a ask lenders specifically about comunidad placements.
hacer FHA casa manufacturada loans require un permanent foundation? Often yes para Title II (casa + terreno mortgages), along con otro real-property y appraisal requirements. Requirements vary por prestamista overlays y el specific transaction.
qué credit score hacer I necesita para un FHA casa manufacturada loan? FHA tiene general minimum guidelines, pero casa manufacturada lenders often apply stricter overlays. el fastest forma a saber es a ask each prestamista their minimum score y debt-a-income requirements para manufactured homes.
cómo hacer I confirm un prestamista es truly un FHA casa móvil prestamista en Texas? Start con FHA-approved status (via HUD resources), then verify ellos actively originate casa manufacturada FHA loans por asking whether ellos offer Title I, Title II, o both, y whether ellos’ve closed similar loans en su county recently.
Talk con un local team ese puede connect usted a el right lenders
si usted querer ayudar narrowing down FHA casa móvil lenders (y choosing un casa ese fits prestamista requirements), Homes2Go San Antonio puede walk usted through el process y connect usted con trusted local financing options.
obtener started here: Homes2Go San Antonio.
 FHA Financing para Mobile Homes: qué’s Covered
 FHA Loan y casa manufacturada: qué Qualifies







