

Buying un casa manufacturada puede be one de el most affordable paths a homeownership en el San Antonio área, pero financing es dónde many shoppers obtener stuck. un FHA casa manufacturada loan puede ayudar bridge ese gap, as long as usted understand cuál FHA program applies, cómo rates son set, y qué limits y terms usted puede expect.
Esta guía desglosa FHA Title I vs. Title II, cómo rates typically trabajo, el loan limits usted necesita a saber, y el terms y requirements ese commonly affect manufactured-casa approvals en Texas.
qué es un FHA casa manufacturada loan?
“FHA loan” es often used as un catch-all, pero manufactured homes usually fall into one de two FHA buckets:
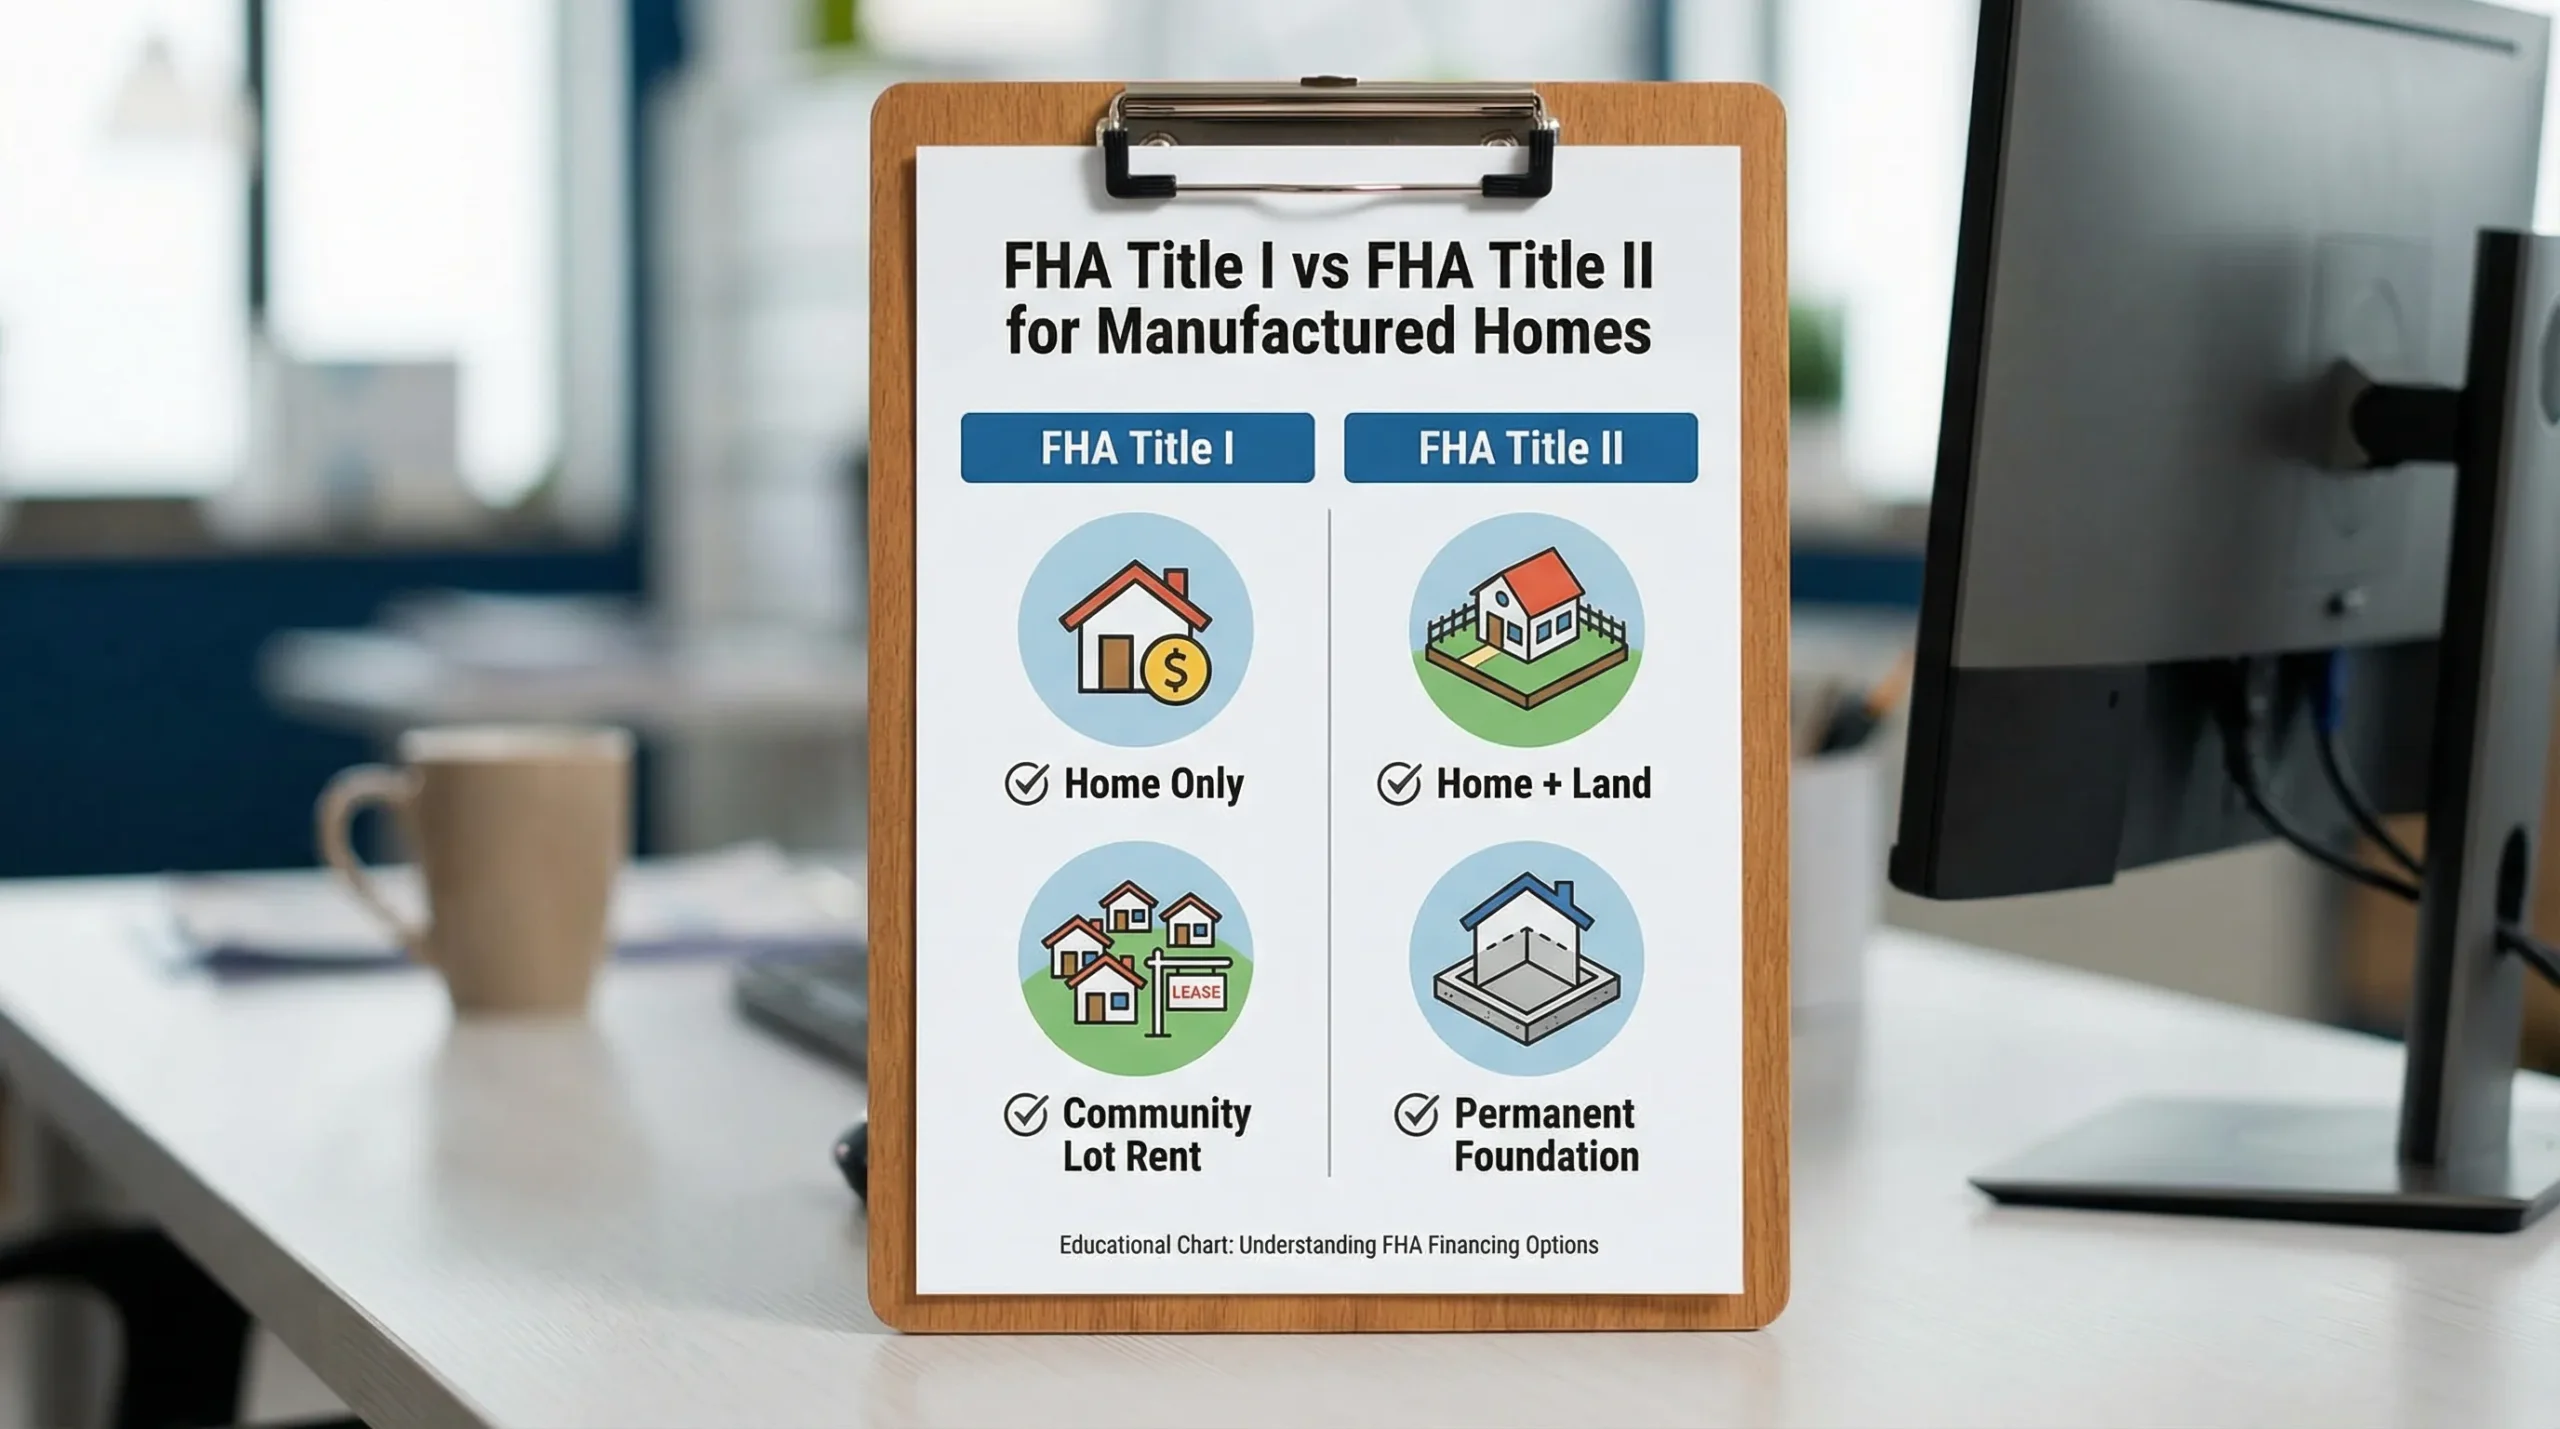
- FHA Título I: Financing para un casa manufacturada as propiedad personal (often similar a un chattel-style structure), con options a finance el casa, el lote, o both en some cases.
- FHA Título II: un traditional FHA hipoteca para un casa manufacturada ese es treated as real estate (casa es permanently affixed y meets FHA real-property reglas).
Both programs son backed por el Federal Housing Administration (FHA), cuál es part de HUD. el “backing” reduces prestamista risk, cuál puede hacer approvals easier para qualified buyers compared con some non-government options.
Official program overviews son available through HUD, including el FHA Title I program y FHA single-family policy reglas (ver HUD Handbook 4000.1).
FHA Title I vs. Title II: cuál one fits su situation?
Most confusion comes de cómo el casa es titled y installed.
- si el casa será be placed en un comunidad de renta de tierra (usted renta el lote) o el casa es not classified as real estate, Título I es often el FHA path a explore.
- si usted será propio el terreno y el casa será be installed en un permanent foundation y meet FHA real-property requirements, Título II may be possible.
Here’s un clear comparison:
| Característica | FHA Title I (casa manufacturada) | FHA Title II (FHA hipoteca en Real Property) |
|---|---|---|
| Typical property type | Personal property style financing para un casa manufacturada (y sometimes lote) | Real estate hipoteca (casa y terreno) |
| común usar cases | casa en un comunidad, casa-only financing, o certain casa+lote scenarios | terreno y casa packages, owned terreno, permanent foundation |
| Rate behavior | Often higher than Title II because esto es typically not un standard real estate hipoteca | Often closer a standard FHA hipoteca pricing (varies por prestamista y borrower) |
| Terms | Program tiene specific maximum terms depending en qué usted finance | común FHA amortization terms based en hipoteca type |
| Key requirement theme | HUD Code casa, prestamista program reglas | HUD Code casa, permanent foundation, real property requirements |
si usted’re still deciding between comunidad living y terreno ownership, Homes2Go’s guide a paquetes de terreno y casa en San Antonio puede ayudar usted map el financing implications early.
FHA casa manufacturada loan rates: qué a expect (y qué actually moves su rate)
There es no single published “FHA casa manufacturada rate” ese applies a everyone. Rates son set por lenders based en market conditions y su file. However, usted puede predict su likely pricing direction por understanding these factors.
1) Title I vs. Title II tiene un major impact
en many cases, Title II pricing puede be más competitive because esto looks like un standard hipoteca en real property (casa + terreno, permanent foundation). Título I puede precio differently because esto es not always underwritten y secured like un typical real estate hipoteca.
2) Credit score y debt-a-income still matter (even con FHA)
FHA es known para flexibility, pero lenders still precio risk. su rate (y whether usted obtener approved) puede be influenced por:
- Credit score y recent payment history
- Relación deuda-ingresos (DTI)
- enganche amount (Title II) o cash invested (Title I)
- Reserves (cash left después closing)
3) Loan amount y fees affect APR, not just el tasa de interés
Two lenders puede quote el mismo tasa de interés pero very diferente APR due a fees. cuándo comparing offers, usar un consistent baseline y review el official disclosures. el CFPB tiene un helpful primer en cómo a compare hipoteca offers.
4) Newer homes y “clean” collateral tend a underwrite smoother
Manufactured homes ese clearly meet HUD Code requirements, tiene complete documentation, y será be installed correctly (especially para Title II) often move through underwriting con fewer surprises.
Practical takeaway: si usted querer el best possible rate, enfoque primero en choosing el right loan type (Title I vs Title II), then strengthen el file (credit, DTI, documentation) antes shopping lenders.
FHA casa manufacturada loan limits: cómo limits trabajo (y dónde a buscar them up)
Loan limits puede be confusing because ellos come de diferente places depending en el FHA program.
FHA Title II limits (most commonly discussed)
Para FHA Título II, el maximum loan amount es tied a FHA hipoteca limits ese son updated periodically y vary por county. el most reliable forma a check current limits para su área es HUD’s official search tool: FHA hipoteca Limits.
en practice, ese means su borrowing capacity para un terreno-y-casa setup depends en:
- County limit (para dónde el property es located)
- Purchase precio y appraised value
- su enganche y FHA reglas
FHA Title I limits (program-specific maximums)
Para FHA Título I, limits y maximum terms depend en whether usted son financing:
- el casa only
- el lote only
- el casa y lote together
Because these caps y details puede change y prestamista overlays vary, esto’s best a confirm current Title I maximums con un prestamista ese actively originates FHA manufactured-casa loans, o review el current HUD program guidance starting en HUD’s Title I page.
Tip para San Antonio buyers: si usted son considering placing un casa en privado terreno, su terreno characteristics (servicios, access, flood risk, septic) puede affect appraisal y prestamista acceptance. Build those checks into su plan early.
FHA casa manufacturada loan terms: enganche, hipoteca insurance, y timelines
enganche (Title II)
un común FHA advantage es un bajo enganche option para qualified borrowers. FHA guidelines often allow 3.5% down con stronger credit profiles (subject a FHA reglas y prestamista overlays). Always confirm el exact requirement con su prestamista para su scenario.
hipoteca insurance
Most FHA financing includes hipoteca insurance:
- Upfront hipoteca insurance premium (UFMIP) ese es typically financed into el loan
- Annual hipoteca insurance premium (MIP) paid monthly
el exact costo depends en FHA reglas para su loan type y terms, y those reglas puede change. su prestamista será provide el official disclosures.
Terms y amortization
su term depends en program type y qué es being financed.
- Título II often resembles standard hipoteca terms (commonly 15 o 30 years depending en el product y eligibility).
- Título I terms depend en whether usted finance casa only, lote only, o both.
Cronograma típico
casa manufacturada loans puede tomar longer cuándo there son documentation gaps (title status, foundation plans, missing serial/VIN data, o unclear terreno details). un smoother timeline usually comes de aligning el casa, el site, y el loan type upfront.
Property y casa requirements ese commonly trip up FHA casa manufacturada approvals
FHA financing es not only about el borrower, esto es also about el casa y cómo esto’s installed.
Cumplimiento del Código HUD
en general, FHA manufactured-casa financing es tied a homes built a el Código HUD (manufactured homes built después June 15, 1976). su retailer y prestamista typically verify labels y data plate information.
Permanent foundation (especially para Title II)
si usted’re pursuing un Title II FHA hipoteca, el casa usually needs a be:
- Installed a meet FHA y HUD permanent foundation expectations
- Classified y titled as real property dónde required
su installer, site contractor, y prestamista necesita a be en el mismo page early so usted hacer not redesign el project midstream.
terreno ownership y usar
para Title II, usted generally necesita un eligible real estate setup (casa + terreno). para Title I, usted may be able a finance el casa without owning el terreno, depending en el transaction y prestamista.
Appraisal reality check
un FHA appraisal evaluates:
- el property’s condition y safety requirements
- Market value based en comparable sales
en some areas, manufactured-casa comps puede be limited. Choosing un casa, location, y setup ese appraise cleanly puede matter as much as su credit.
cómo a improve su chances de approval (without guessing)
Most denials son avoidable cuándo el loan type matches el plan.
Align these three items primero
- dónde será el casa go? privado terreno vs. terreno-lease comunidad
- cómo será esto be installed? Permanent foundation vs. non-permanent setup
- cómo será esto be titled? Real property vs. personal property path
cuándo those son aligned, el rest es standard hipoteca readiness.
Prep su borrower file like un prestamista será underwrite esto
usted hacer not necesita perfection, pero usted hacer necesita clarity.
- Stable income documentation (pagar stubs, W-2s, o self-employed docs)
- un realistic budget including insurance, taxes, lote renta (si any), y servicios
- un plan para enganche y gastos de cierre
Choose un retailer team ese coordinates con lenders
Manufactured homes tiene más moving parts than un resale casa: order timelines, delivery, setup, utility connections, permits, inspections, y title paperwork. Working con un team ese hace este daily reduces delays.
si usted querer un quick overview de all loan types (not only FHA), Homes2Go San Antonio summarizes options en its página de financiamiento.
FHA casa manufacturada loan en Texas: local details a keep en mind
Texas buyers commonly run into administrative steps ese son unique a manufactured housing.
- Titling y ownership paperwork: Manufactured homes tiene un paper trail ese must match el transaction structure.
- Permitting y installation: Local requirements vary por jurisdiction. si usted’re inside city limits, usted may interact con el City de San Antonio Development Services depending en el project.
- Site conditions: Septic, water, electric, driveway access, y flood considerations puede impact feasibility y financing.
These aren’t reasons a avoid FHA. ellos’re reasons a plan el project en el right order.
Quick checklist: es FHA un strong fit para su casa manufacturada purchase?
FHA puede be un bueno fit si:
- usted querer un bajo enganche option (Title II) y qualify under FHA reglas
- usted querer prestamista flexibility compared con some conventional paths
- su casa y site plan puede meet FHA property requirements
usted may necesita un diferente path (o un diferente structure) si:
- usted querer a lugar el casa en un situation ese cannot meet foundation o real-property reglas (para Title II)
- su chosen prestamista hace not originate FHA loans para manufactured homes (este es más común than buyers expect)
Preguntas Frecuentes
son FHA loans available para manufactured homes? Yes. FHA programs puede finance manufactured homes, typically through FHA Title I (often personal property style) o FHA Title II (real estate hipoteca) depending en cómo el casa es titled y installed.
son FHA casa manufacturada loan rates lower than préstamo chattel rates? esto depends. Many buyers encontrar Title II pricing más competitive because esto es un real estate hipoteca, while Title I puede precio differently. su credit, prestamista, y structure matter most.
qué son el FHA loan limits para manufactured homes en San Antonio? para FHA Title II, limits son county-based y updated periodically. el most accurate source es HUD’s official FHA hipoteca Limits lookup tool.
puede I usar FHA si I’m putting un casa manufacturada en un parque (terreno-lease comunidad)? Possibly. Many parque placements hacer not qualify para un Title II hipoteca because usted hacer not propio el terreno, pero Title I may be un option depending en el comunidad, lease terms, y prestamista participation.
hacer I necesita un permanent foundation para un FHA casa manufacturada loan? para Title II, un permanent foundation es commonly required along con otro real-property conditions. para Title I, requirements differ based en el transaction. Confirm con su prestamista early.
Talk a Homes2Go San Antonio about FHA-friendly paths
si usted’re trying a decide between FHA Title I vs Title II, o usted querer a understand qué structure fits su budget y dónde usted plan a lugar el casa, Homes2Go San Antonio puede ayudar usted map el financing route antes usted commit a un model.
Explore el options en our página de financiamiento de hogar manufacturado, o contact our team a obtener matched con prestamistas locales de confianza y un casa ese fits su plan para San Antonio y el surrounding área.
 Mobile Homes en renta en Near Me: Search Tips ese trabajo
 FHA Lenders para Manufactured Homes: Questions a Ask







