If you are trying to buy a manufactured home with FHA financing, the FHA manufactured home down payment is usually one of the first numbers you want to understand. The good news is that FHA loans are designed to help buyers with limited cash savings, but the actual amount you need depends on the loan type, your credit profile, whether land is included and how the home will be titled.
For San Antonio buyers, that makes early planning especially useful. A manufactured home purchase can involve the home, delivery, installation, land, a community lot or a permanent foundation. FHA may help make the purchase more accessible, but the down payment is only one part of the total cash needed to close.
What the FHA manufactured home down payment actually covers
Your down payment is the portion of the purchase price you pay upfront instead of borrowing. It reduces the loan amount and gives the lender a starting equity position in the home. With FHA financing, this is often called the minimum required investment for certain loan types.
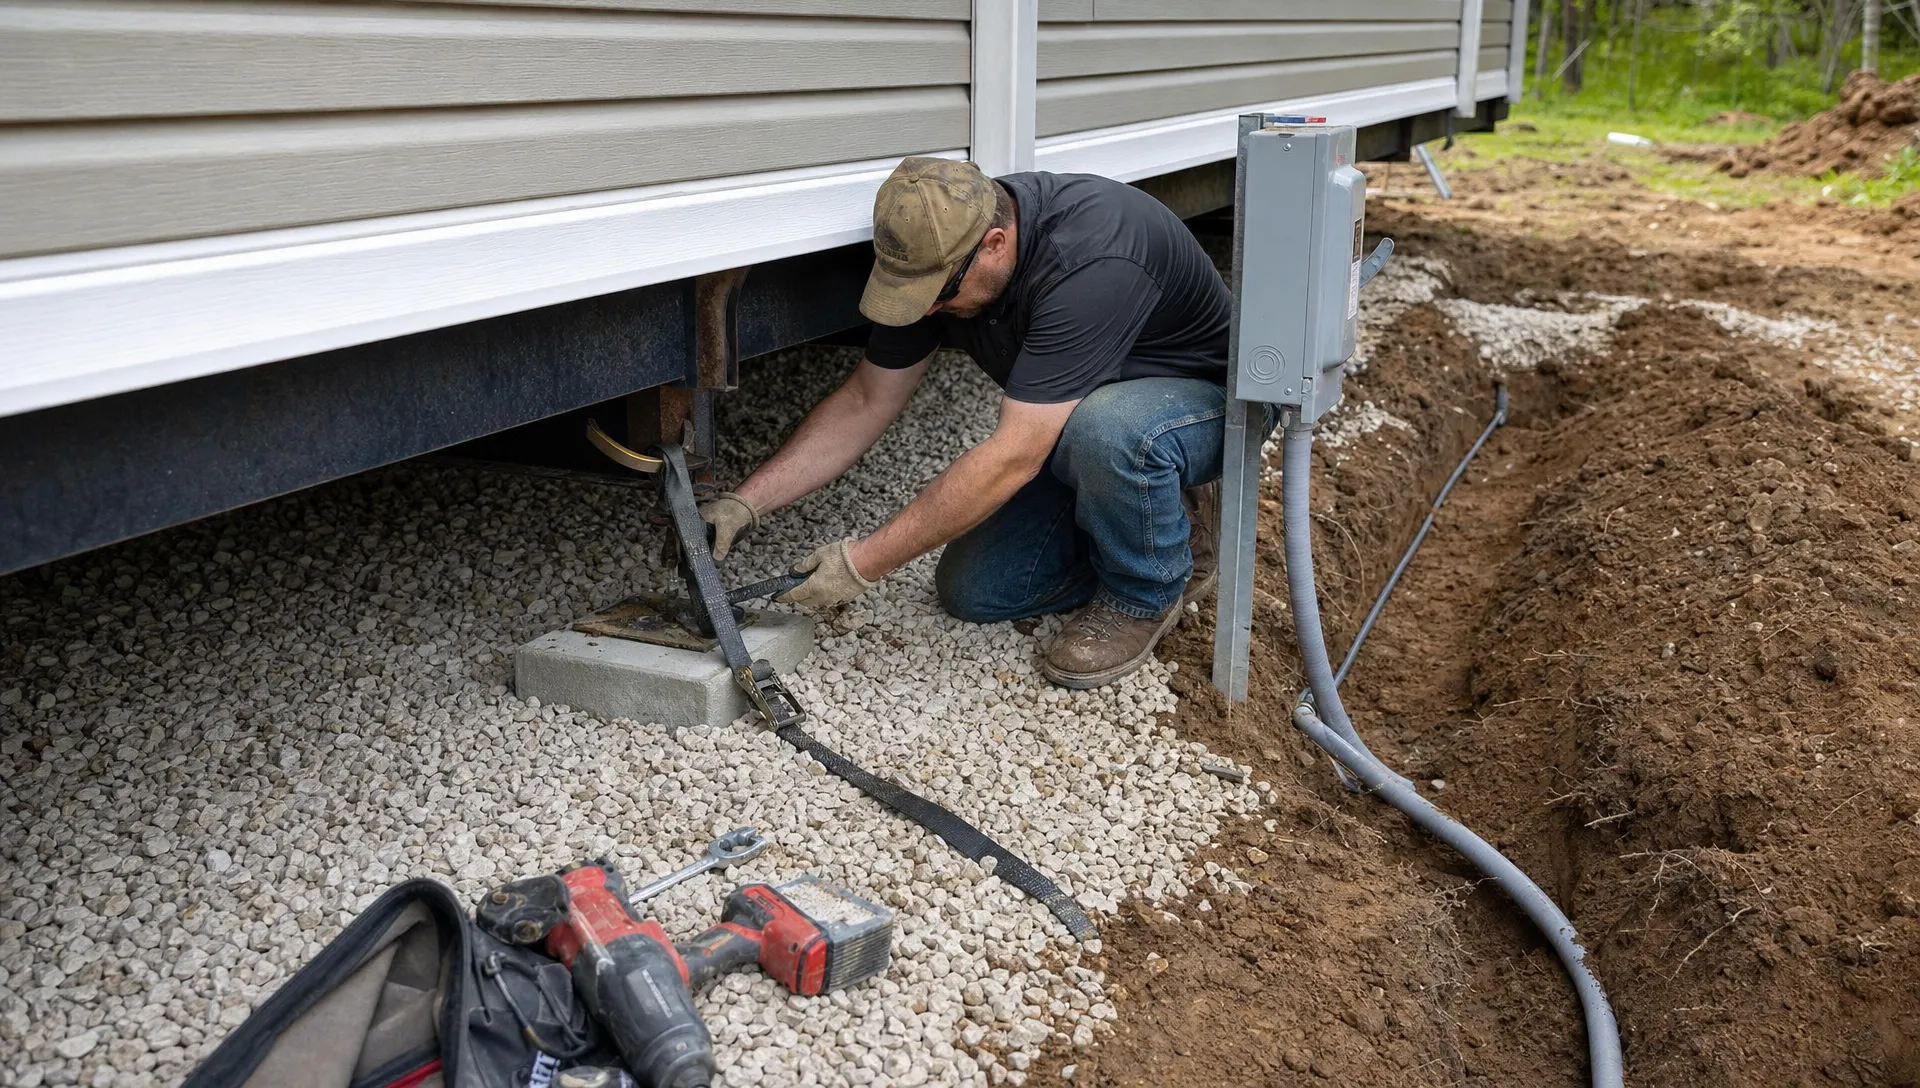
The down payment is not the same as closing costs. Closing costs can include lender fees, title work, appraisal fees, inspections, recording fees, prepaid taxes, homeowners insurance and mortgage insurance items. If you are buying a manufactured home that will be installed on land, site work and foundation documentation may also affect your total cash plan.
A practical way to think about the FHA manufactured home down payment is this: it is the required buyer contribution toward the home purchase, but it does not automatically cover every dollar you will need before move-in.
Title II vs. Title I: why the loan type matters
FHA financing for manufactured homes is not one single product. The down payment can change depending on whether your lender uses FHA Title II or FHA Title I.
FHA Title II for a manufactured home classified as real property
FHA Title II is commonly used when the manufactured home and land are financed together as real property. In this setup, the home usually needs to meet HUD Code standards, be permanently affixed to an approved foundation and satisfy lender, appraisal and title requirements.
For Title II, the FHA manufactured home down payment often follows the standard FHA purchase structure: 3.5% down for eligible borrowers with a credit score of 580 or higher. FHA rules generally require 10% down for borrowers with credit scores from 500 to 579, although many lenders set stricter credit score minimums.
That 3.5% figure is a minimum, not a guarantee. Your lender still evaluates income, debts, credit history, the property and the full file. If you want the broader eligibility rules beyond down payment, Homes2Go has a plain-English guide to FHA loan requirements for manufactured homes.
FHA Title I for home-only or manufactured home purchases
FHA Title I may be used for manufactured home purchases where the structure is financed separately from land, such as a home placed in an approved leased-lot community. According to HUD’s Title I manufactured home loan insurance information, borrowers must have a minimum cash investment, commonly described as at least 5% for manufactured home purchases under that program.
Title I can be useful in situations where a buyer is not purchasing land, but lender availability, loan limits and community requirements matter. If the home will sit in a manufactured home community, ask early whether the lender, community and home all fit the same financing path.
How to estimate your cash needed before shopping
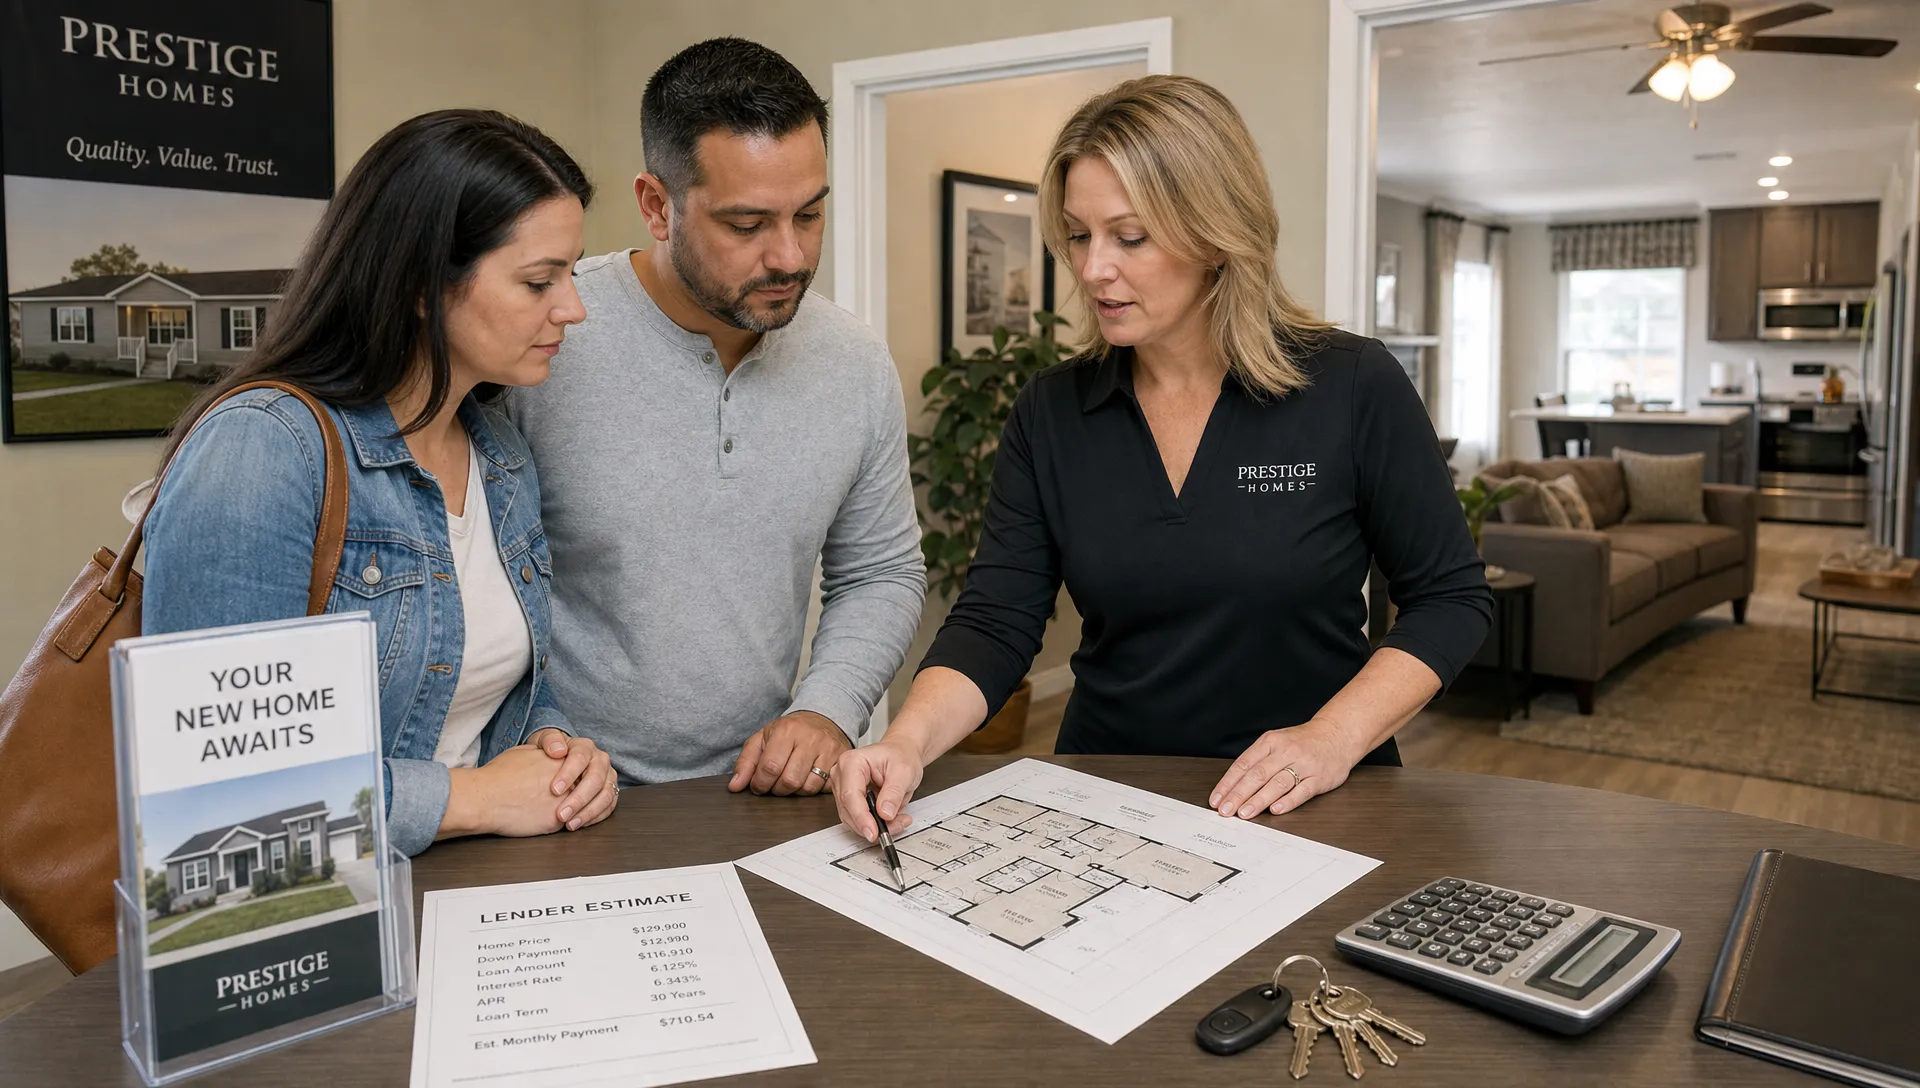
Start with the purchase structure, then estimate the minimum down payment, then add closing costs and any setup costs not financed into the loan. When you estimate the FHA manufactured home down payment, use real quotes instead of rough guesses as soon as possible because freight, setup, options and site requirements can change the final price.
Here are simple examples to show the math. These are not quotes or approvals, and actual financing depends on lender review.
| Purchase example | Possible FHA path | Down payment estimate | What to remember |
|---|---|---|---|
| $150,000 home and land package | Title II | 3.5% = $5,250 if eligible | Closing costs are separate |
| $120,000 manufactured home without land | Title I | 5% = $6,000 under common HUD Title I guidance | Lender and community rules matter |
| $220,000 home and land package | Title II | 3.5% = $7,700 if eligible | Property must meet FHA and lender standards |
| $180,000 purchase with 10% required | Title II or lender overlay situation | 10% = $18,000 | Credit profile can change cash needed |
For Title II loans, FHA also has mortgage insurance. The upfront mortgage insurance premium can often be financed into the loan amount, but that does not replace the required down payment. Financing it can reduce cash due at closing, but it can also raise the loan balance and monthly payment.
What can count toward the down payment?
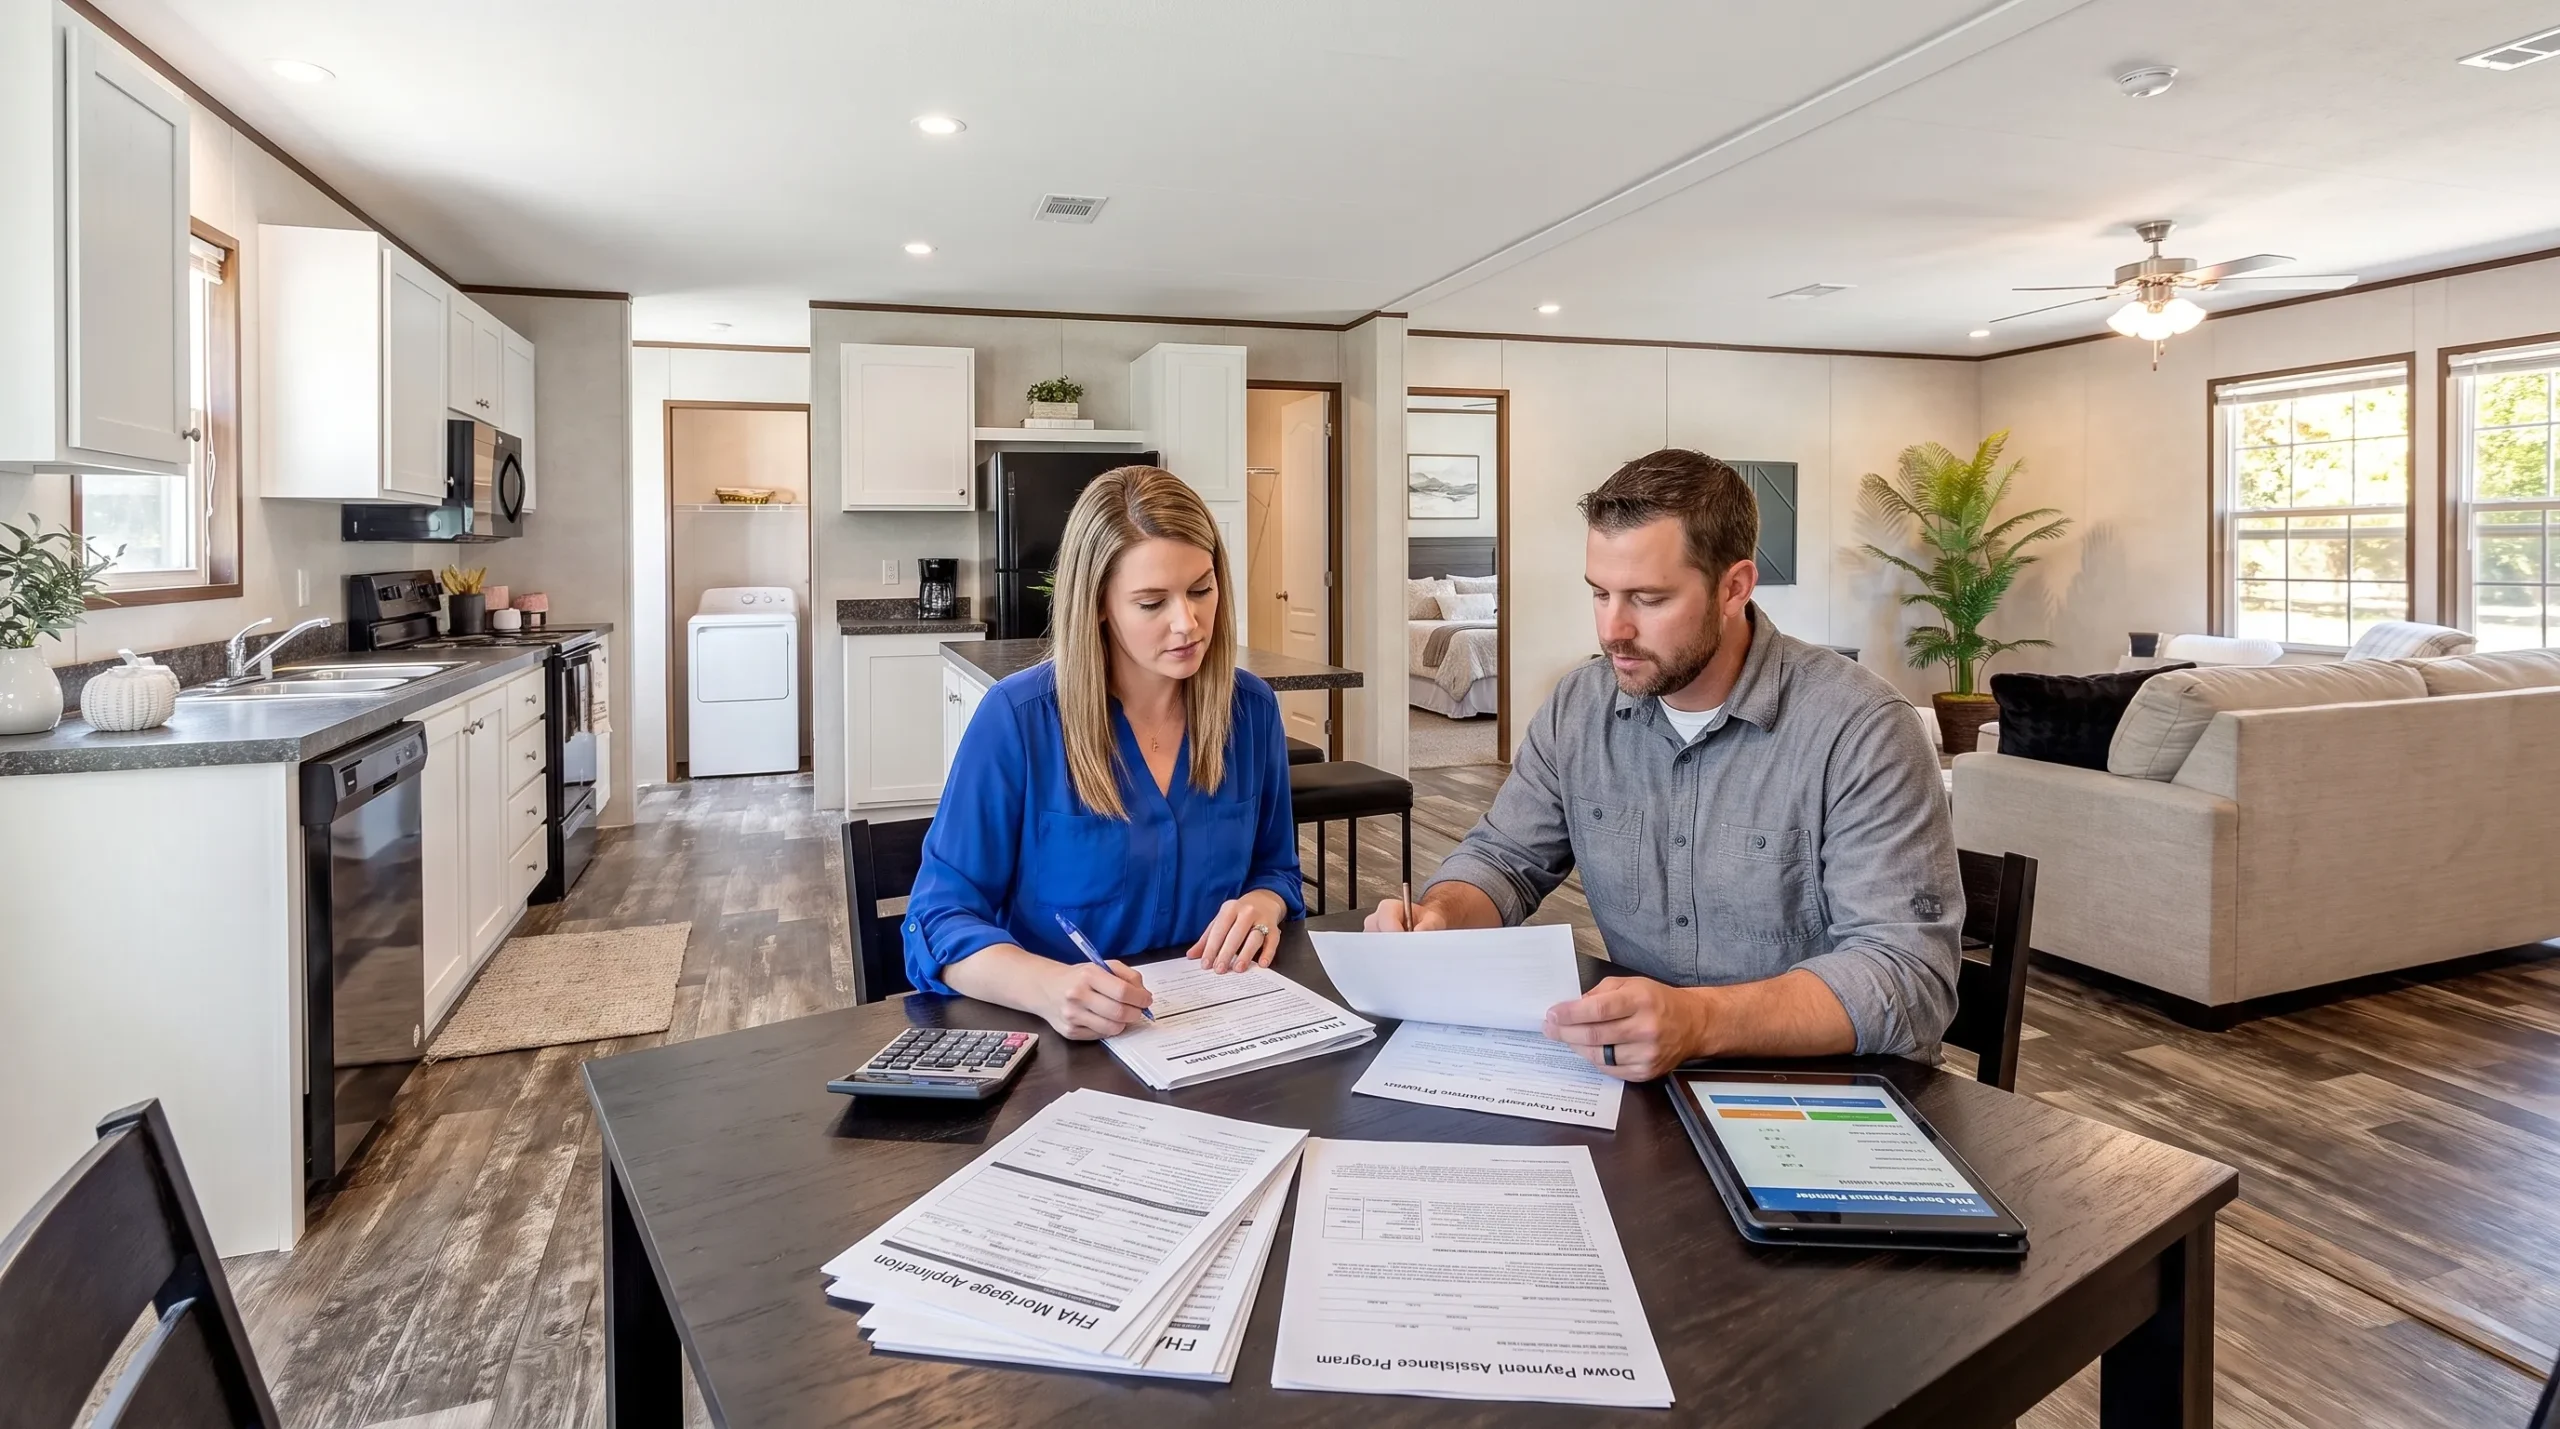
The FHA manufactured home down payment does not always have to come only from your personal checking account. FHA rules may allow approved gift funds, acceptable down payment assistance and documented personal savings, subject to lender review.
Documentation is the key. Lenders need to verify where the money came from and whether it is allowed. Large unexplained deposits, cash that cannot be sourced or last-minute transfers from an ineligible source can slow down approval.
Common acceptable sources may include:
- Personal savings from checking, savings or investment accounts
- Gift funds from an eligible donor, properly documented
- Approved down payment assistance programs, if your lender and loan type allow them
- Proceeds from selling an asset, with a clear paper trail
Seller credits are different. A seller may be able to help with certain eligible closing costs within FHA limits, but seller credits generally do not satisfy the buyer’s required down payment. Ask your lender to separate these numbers on a worksheet so you can see the true cash-to-close estimate.
Home choice can change your down payment plan
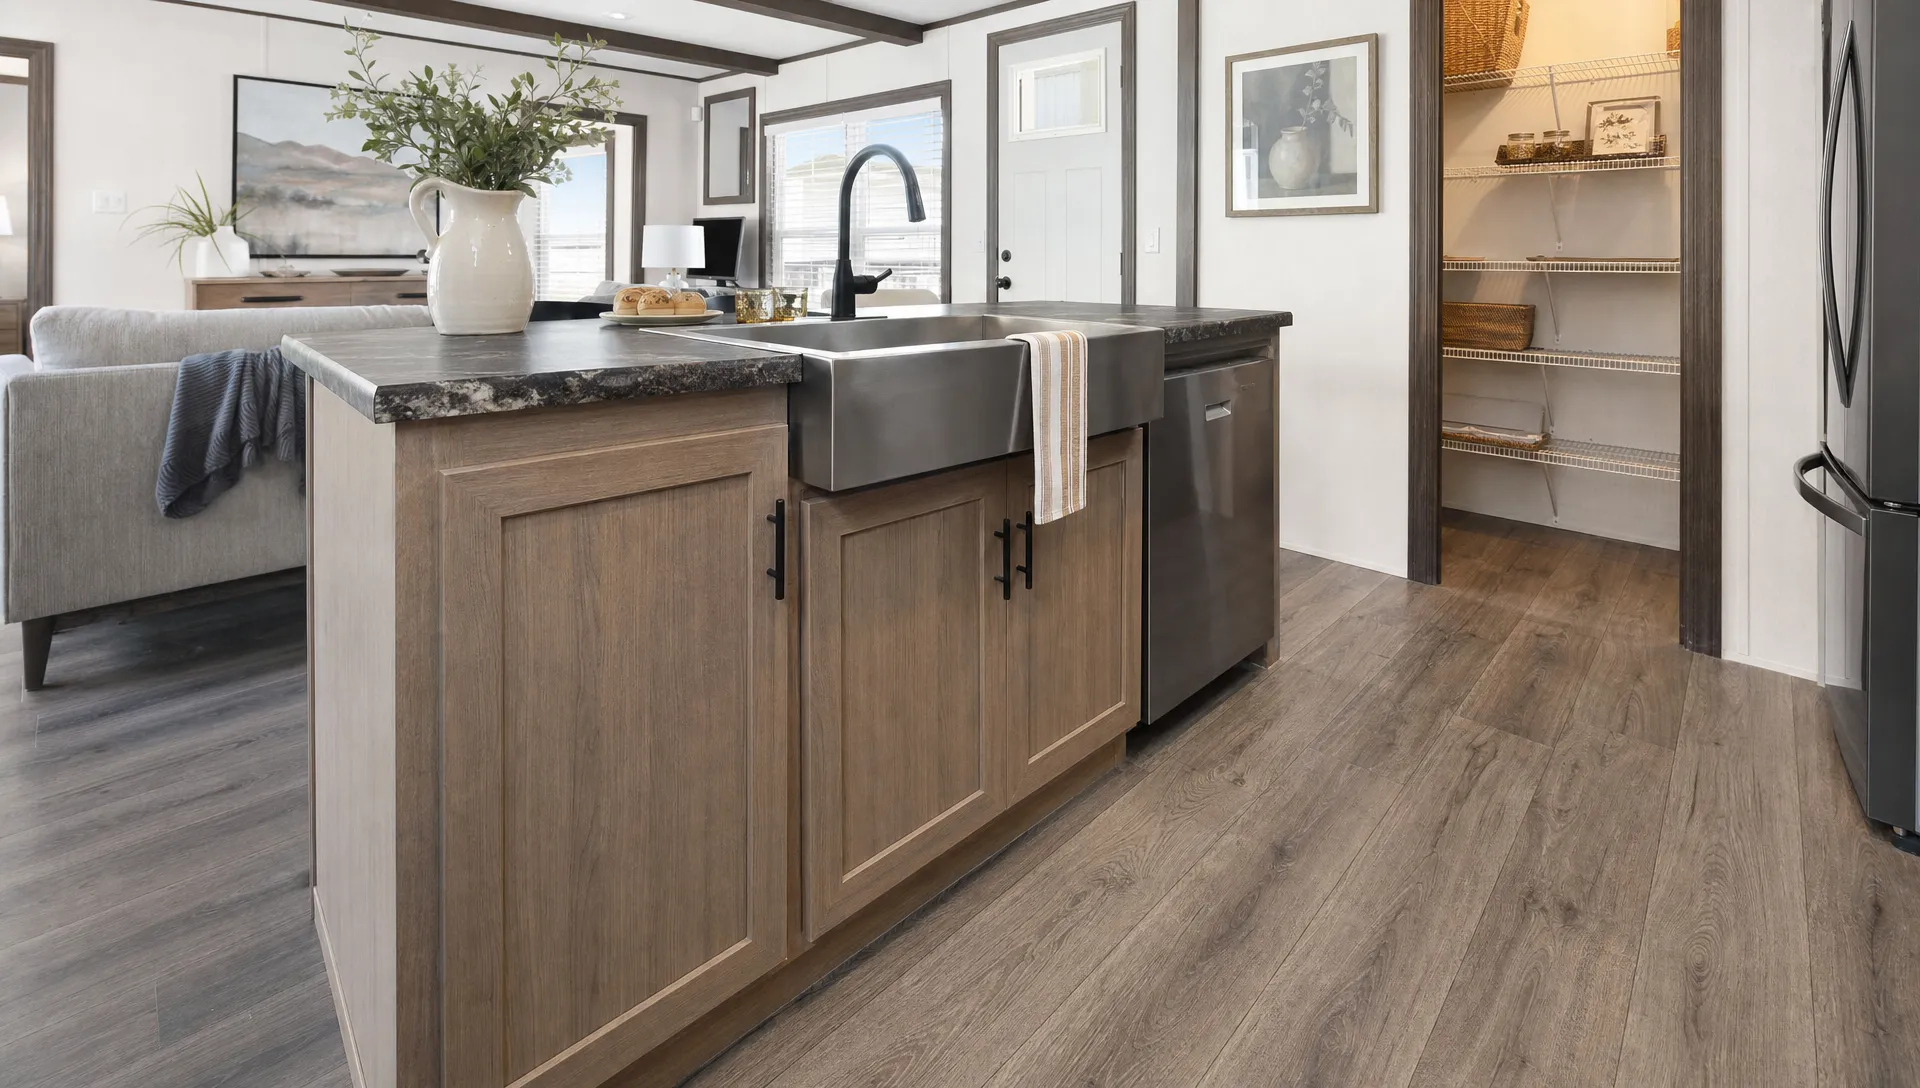
The floor plan you choose affects more than the layout. Since the down payment is calculated from the purchase price, a larger home, upgraded features or a different installation plan can raise the amount of cash needed. The FHA manufactured home down payment should be reviewed alongside monthly payment, utility expectations, insurance and community or land costs.
For example, a family needing a spacious doublewide may want to compare the 3-bedroom, 2-bath Champion Albany, which offers 1,456 sq ft in a 30 ft 4 in x 52 ft layout. Another buyer may prefer a more compact 3-bedroom, 2-bath option like the Legacy Heritage H-1680-32J, which offers 1,193 sq ft in a 16 ft x 80 ft layout.
Neither example tells you the exact down payment without a current purchase price and lender review. The useful lesson is that comparing floor plans early lets you compare financing scenarios before you emotionally commit to one home.
Homes2Go San Antonio can help shoppers look at available models, detailed floor plans, energy-efficient designs and move-in ready options while also encouraging early financing conversations with trusted local lenders.
Common mistakes that make FHA down payments harder
Many buyers focus only on the percentage and forget the conditions attached to the loan. FHA approval for manufactured homes depends on the borrower, the home and the site. A low down payment does not help if the home, title or foundation does not satisfy the program being used.
One common mistake is shopping for homes without knowing whether the lender is considering Title I or Title II. Another is assuming that a manufactured home in any community automatically qualifies. If land is leased, the financing path may be different than a home-and-land purchase.
The FHA manufactured home down payment can also feel larger than expected when buyers forget closing costs. A 3.5% down payment on a qualified Title II purchase may sound simple, but appraisal fees, title charges, insurance, prepaid taxes and other costs still need to be accounted for.
If you are looking at a new manufactured home that involves land preparation or construction-style steps, review how FHA treats the process. Homes2Go’s guide to FHA construction loans for manufactured homes explains when construction-to-permanent financing may be relevant.
A simple checklist before you apply
Before you submit a full loan application, gather enough information to let a lender give you a realistic estimate. The goal is not just to know whether FHA financing is possible, but to know how much cash you should keep available through closing.
Use this checklist before you shop seriously:
- Ask whether the lender is evaluating Title I, Title II or another loan option
- Confirm the minimum down payment percentage based on your credit profile
- Get a written estimate of closing costs, not just the down payment
- Ask whether gift funds or assistance programs are allowed for your file
- Confirm whether the home will be titled as personal property or real property
- Review land, lease, foundation and installation requirements early
- Keep your funds documented and avoid unexplained deposits before closing
A little preparation can prevent expensive surprises. It also helps you compare homes based on the full cost of ownership, not just the listed home price.
Frequently Asked Questions
What is the minimum FHA manufactured home down payment? For many FHA Title II manufactured home purchases, the minimum may be 3.5% if the borrower has a qualifying credit score of 580 or higher. FHA Title I manufactured home loans commonly require at least 5% cash investment. Lenders can have stricter rules.
Can closing costs be rolled into an FHA manufactured home loan? Some costs, such as the upfront mortgage insurance premium on many FHA Title II loans, may be financed. Other closing costs may need to be paid at closing or covered by allowed credits. Your lender should provide a cash-to-close estimate.
Can I use gift money for the down payment? FHA may allow gift funds from eligible donors if the money is properly documented. The lender will need a paper trail and a gift letter that meets its requirements.
Does FHA finance manufactured homes in land-lease communities? It can be possible under certain loan structures, especially FHA Title I, but the lender and community must meet applicable requirements. Ask before choosing a lot or signing community paperwork.
Is the down payment based on the home price or the home and land price? It depends on the loan structure. If the manufactured home and land are financed together under Title II as real property, the calculation is usually based on the eligible purchase amount for that property transaction.
Plan your FHA down payment before choosing a home
The FHA manufactured home down payment can make homeownership more accessible, but it works best when you understand the whole picture: loan type, credit profile, home eligibility, land status, closing costs and documentation.
If you are shopping in the San Antonio area, Homes2Go can help you compare manufactured home models and connect your home search with the financing questions that matter early. Explore available homes at Homes2Go San Antonio and talk with the team about floor plans, communities and next steps for your buying timeline.
 Modern Manufactured Home Designs That Feel Built for Today
 How to Buy a Manufactured Home on Land You Own